The key to understanding the market's muted response lies in what Treasury Secretary Scott Bessent deliberately withheld: major Chinese banks. This asymmetry between the rhetoric and enforcement reveals a critical insight for the energy ETF trader.
The Sanctions That Moved Oil the Wrong Way
The market's muted response to Operation Economic Outcast called the bluff. Bessent branded the campaign a strategy to strangle Tehran's economy into submission. The initiative targets nearly 60 Iran-linked entities, individuals, and vessels across UAE, Hong Kong, China, Singapore, and Europe. It spans digital assets, technology, gold, aviation, and shipping.
Bessent warned that countries not joining the US sanctions would share in the isolation of Iran. Still, prices did not react as the rhetoric might have implied.
Why the Market Shrugged
Traders treated the financial squeeze as a milder danger to physical barrels than an armed confrontation. The campaign was described by experts as potentially intended as a warning shot. Bessent gave no specific details on the measures. The most punitive option — moving directly against large Chinese banks or major international companies linked to Iranian trade — was the exact lever Bessent chose not to pull.
This deliberate restraint highlights the administration's calculation: to avoid destabilizing the global financial system, which could have broader economic consequences. The sanctions may sound apocalyptic, but their enforcement remains conditional and measured.
The War Premium Still Baked into Energy
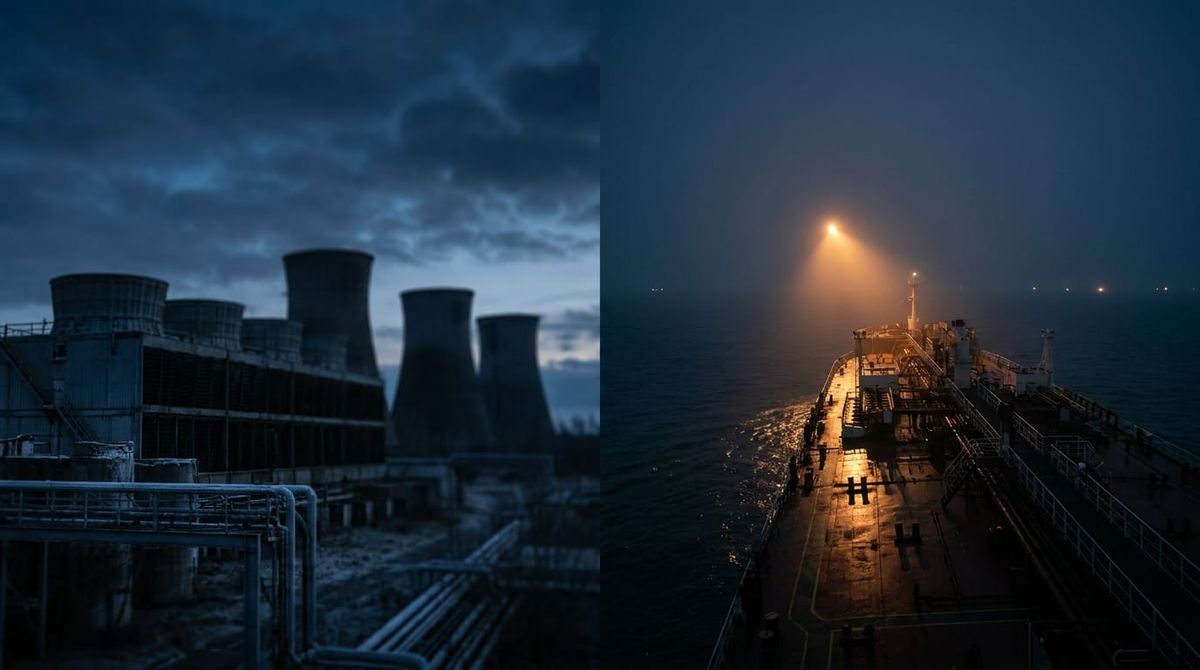
Energy exposure rests on a geopolitical bid. The Strait of Hormuz remains a critical chokepoint, with Tehran blocking most traffic through the strait. The energy sector’s performance has been closely tied to the perception of ongoing disruption.
However, the market’s response to the sanctions suggests that traders are pricing in the possibility of de-escalation. If the situation stabilizes, the war premium embedded in energy prices could unwind quickly. This introduces a tail risk for holders of energy ETFs, as their returns depend on the continuation of geopolitical tension.
The Hidden Long Position in Energy ETFs
The sanctions non-reaction reveals the asymmetry in energy exposure. Holders are effectively long a war premium that de-escalation would unwind fast. This is de-escalation tail risk, not a supply shock.
Peace talks remain stalled, which has kept the premium alive for now. The energy trade is sitting on a de-escalation trapdoor that most holders haven’t priced.
Sanctions as Diplomacy, Not a Supply Event
Markets may price sanctions as diplomacy-by-other-means rather than a supply event, given experts view the operation as a possible warning shot. The sanctions were built to sound like the end of the story, but for energy exposure the real signal lives almost six months into the Hormuz crisis, not in the D-Day rhetoric.
Watch how equity ETFs like XLE track corporate cash flow while futures-linked products bleed roll decay — the structure decides who survives a de-escalation. The rhetoric is loud, but the enforcement stayed measured, and that gap is the whole trade.
Watch the strait, not the podium: pull up a Hormuz shipping-traffic tracker and check whether the chokepoint reopens before you touch your energy exposure. | 


Comments ()